Dollar Higher Despite Drop in October Hike Pricing
Soft PCE Data, Stronger GDP
The US Dollar is continuing to push higher today despite further data weakness seen yesterday and a fresh drop in market pricing for an October rate hike. Yesterday, monthly core PCE was seen at 0.2%, below the 0.3% the market was looking for, fuelling a drop in market pricing (CME group Fed Watch) for an October hike from 50% to 39%. However, USD remains firmly bid on the back of the data. This can be attributed to the unexpected strength in the final quarterly GDP figure which jumped to 2.2% from 1.5% prior and expected. Additionally, the ADP employment number came in at 90k, up from 36k prior and above the 73k the market was looking for. Given the strength in those two data points and the rally in USD, the drop in October tightening expectations feels disjointed.
Next US Data Due
Today, traders will be watching the latest weekly job claims number as well as the ISM manufacturing print. If seen on the healthy side, this should keep the USD rally intact into tomorrow’s headline NFP release. If tomorrow’s data surprises to the upside, this should pull tightening expectations higher again, providing fresh fuel for a breakout move in DXY. If this data comes in weak, however, the USD rally should correct as tightening expectations fall further.
Technical Views
DXY
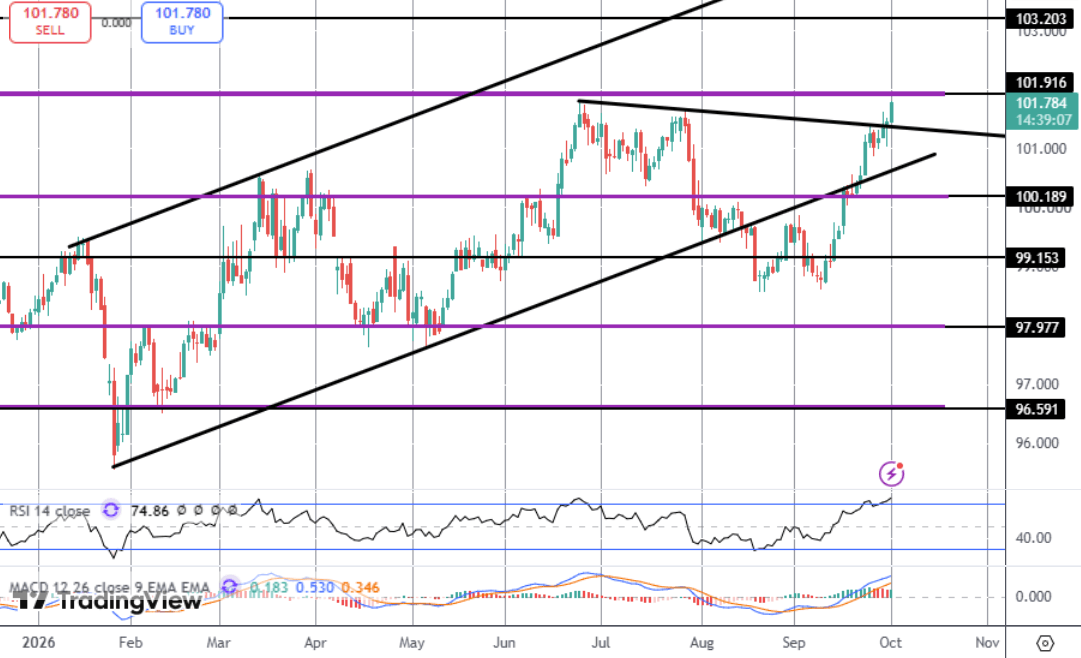
The rally in the index has seen price trading back up to test the YTD highs and 101.91 level, piercing above the bear trend line from YTD highs. This is a key resistance zone and a break higher here will turn the focus to 103.20 as the next bull target. Downside, the 100 level remains the key support to watch with the outlook remaining bullish while price holds above there.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% and 73% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
With 10 years of experience as a private trader and professional market analyst under his belt, James has carved out an impressive industry reputation. Able to both dissect and explain the key fundamental developments in the market, he communicates their importance and relevance in a succinct and straight forward manner.